Amanda Blanc, CEO of Aviva, has warned that homes currently being built in high-risk areas across England are on a path to becoming uninsurable. As the insurance industry faces mounting climate-related pressures, there is growing concern that thousands of new properties are being constructed in locations where they may eventually lose financial protection.
The core of the risk lies in the looming 2039 expiration of Flood Re, a joint initiative between the government and insurers that subsidizes premiums for households at high risk of flooding. This scheme was established to ensure insurance remains affordable, but it was designed as a temporary measure with a legal mandate to exit the market in 15 years.
For homeowners and buyers today, this creates a “ticking clock” scenario. A standard 25-year mortgage taken out in the mid-2020s would still be active when the subsidy vanishes in 2039. If a property becomes uninsurable at that point, its value could be severely impacted, as most lenders require valid buildings insurance as a non-negotiable condition of the loan.
The Conflict Between Housing Targets and Resilience
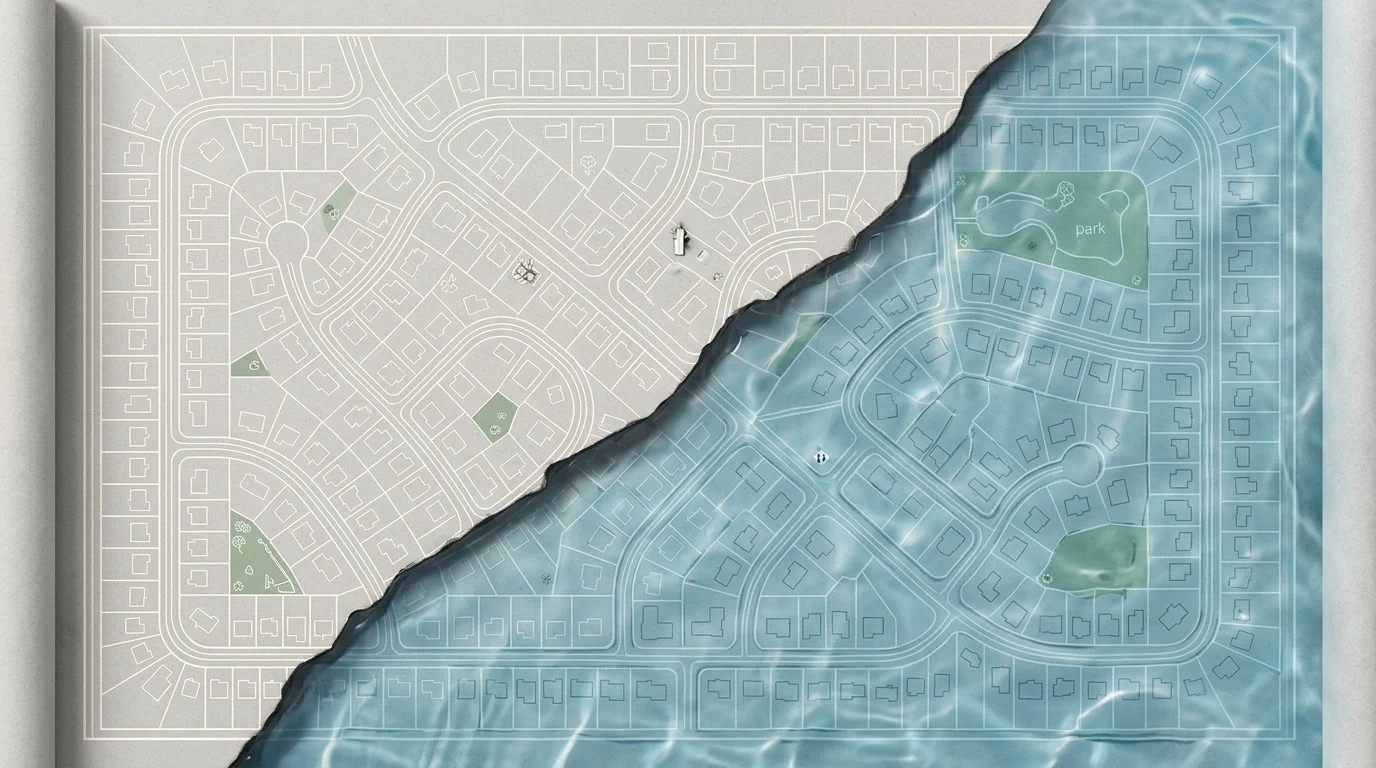
According to Aviva, approximately one in 13 new homes in England were built on land at high risk of flooding between 2013 and 2023. Despite these risks, the pressure to meet ambitious housing targets remains high. The UK government is currently aiming to deliver 1.5 million new homes, a goal that insurers argue frequently clashes with the need for stricter flood resilience standards within the National Planning Policy Framework (NPPF).
Blanc has suggested that the UK’s planning system is “for sure” prioritizing immediate housing needs over long-term climate adaptation. While developers often implement sustainable drainage systems (SuDS) to mitigate risk, major insurers maintain that the fundamental choice of location remains the primary failure in the current planning process. If homes continue to be built on floodplains, the financial burden of future climate events may eventually become too high for the private insurance market to absorb without government intervention.
Preparing for the Post-Subsidy Market
To manage the transition toward 2039, the insurance industry has introduced initiatives such as “Build Back Better.” This framework allows insurers to pay for specific flood resilience measures—such as moving electrical sockets higher up walls or installing water-resistant flooring—rather than simply performing like-for-like repairs after a flood. The objective is to make high-risk homes naturally resilient enough to remain insurable in an open, unsubsidized market.
However, the scale of development on floodplains over the last decade suggests that many properties may still struggle to find affordable coverage once the safety net is removed. This leaves current buyers in a difficult position, as properties marketed as safe today may face a “financial cliff” before their mortgages are fully paid off. Experts suggest that prospective owners should scrutinize long-term flood projections and the specific resilience features of a property before committing to a decades-long financial obligation.