Average diesel prices across Europe reached a record €2.159 per litre in late September 2026. The price surge has begun to manifest as physical scarcity in parts of the continent; in France, approximately 11% of petrol stations reported fuel shortages by the end of the month. In the United Kingdom, the average price for diesel hit 198.32p per litre on September 28.
While the conflict in Ukraine remains a factor, a convergence of refining bottlenecks, geopolitical blockades in the Middle East, and potential policy shifts in the United States have created a more complex supply crisis. Although global crude oil production has remained relatively steady, the cost of refining that crude into usable diesel—known as the “crack spread”—surpassed $100 per barrel in the Atlantic Basin for the first time on record this year.
Refining Bottlenecks and Middle East Disruptions
The disconnect between crude oil prices and diesel costs is driven largely by a global shortage of refining capacity. Financial analysts note that the diesel crack spread has exposed the fragility of the current refining infrastructure, which is struggling to meet demand even as non-OPEC production grows in the Americas.
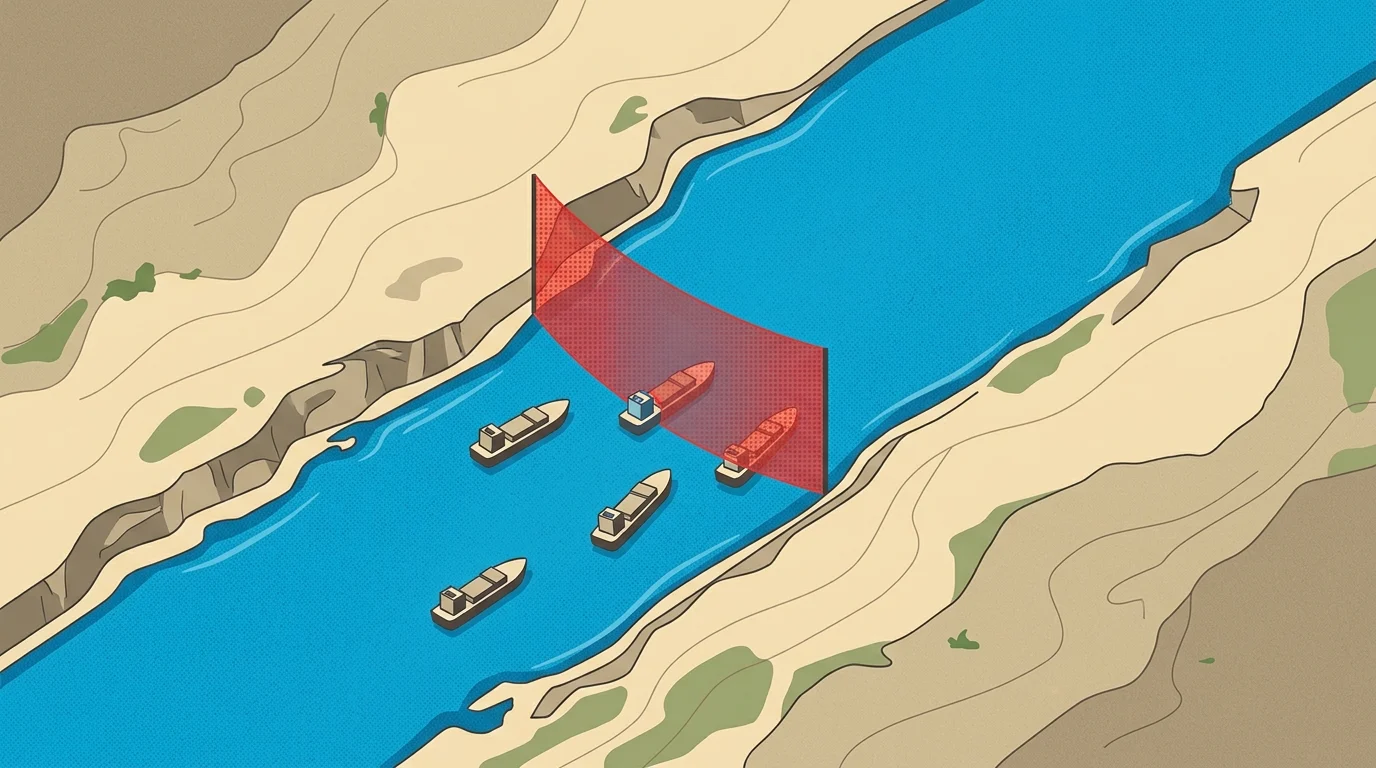
Supply lines from the Middle East, a critical source for European imports, have simultaneously faced severe restrictions. Shipping traffic through the Strait of Hormuz collapsed to just three vessels per day in September 2026, a sharp decline from the pre-conflict average of 64. This maritime bottleneck was exacerbated by the temporary closure of Saudi Arabia’s East-West Pipeline following drone strikes in the Riyadh and Madinah regions earlier in the month. This pipeline was previously considered the primary bypass for fuel transport should the Strait of Hormuz be compromised.
Further tightening the market, Russia has extended its ban on most diesel exports through late October 2026, removing a significant volume of fuel from the international spot market.
The U.S. Export Ban Threat
Pressure on the Atlantic market intensified on September 27, 2026, when U.S. President Donald Trump stated his administration is “very seriously” considering a ban on diesel exports. The proposed move is intended to lower domestic U.S. diesel prices, which reached a record $6.53 per gallon on September 22, ahead of the upcoming midterm elections.
Analysis of such a move suggests significant secondary consequences. Financial modeling from Goldman Sachs warned that while a diesel export ban might provide temporary domestic relief for that specific fuel, it could trigger a $0.30 per gallon spike in gasoline prices within ten weeks due to the disruption of integrated refining flows. For Europe, the loss of U.S. diesel exports would remove one of the last remaining buffers against the current supply deficit.
Logistics Failures in Central Europe
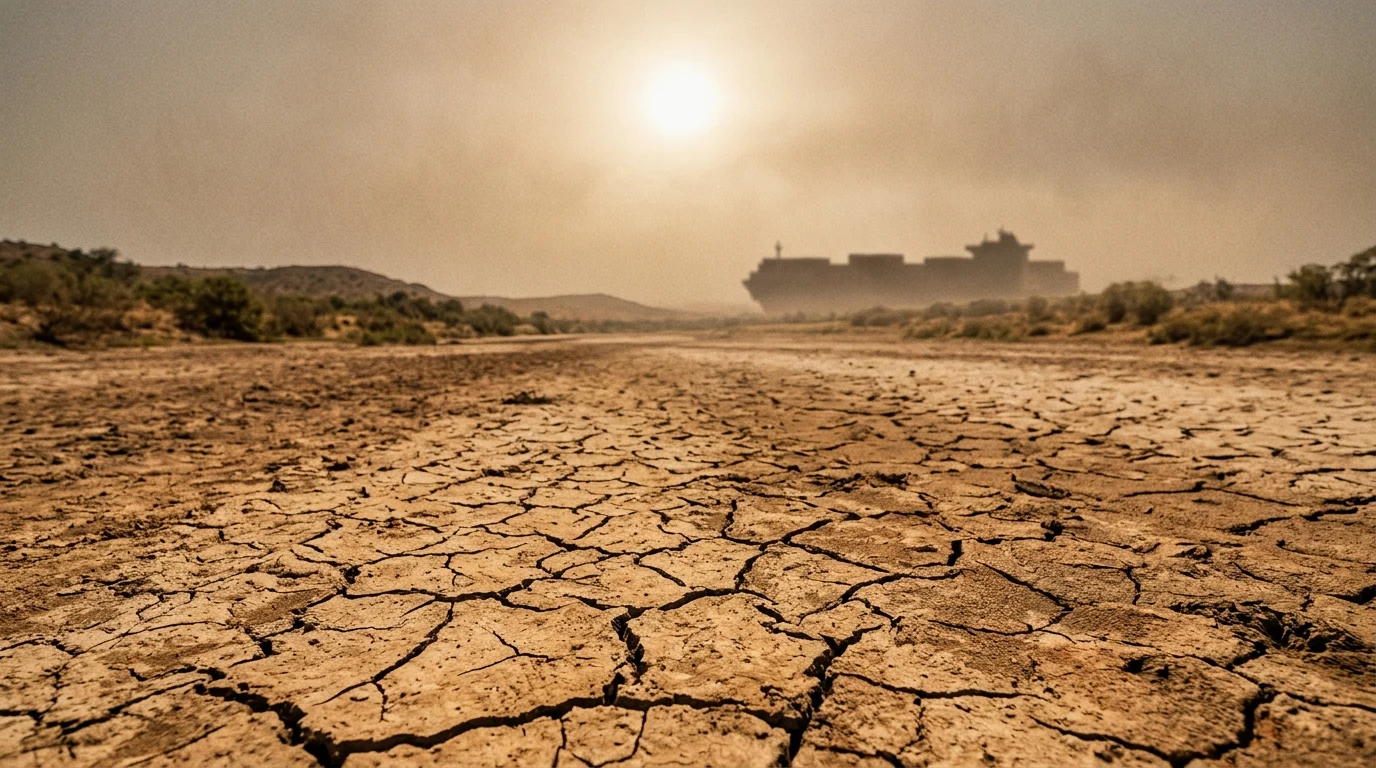
Beyond global trade routes, local logistics are failing to move existing inventories to where they are most needed. In Germany, the Rhine River—a vital artery for fuel barges supplying inland industry—fell to a near-record low of 11cm at the Kaub chokepoint on September 24.
At these water levels, most barges are unable to carry full loads, significantly increasing the cost of inland transport and preventing the replenishment of regional fuel depots. This logistical constraint, combined with the broader refining and geopolitical pressures, suggests that European diesel prices may remain decoupled from crude oil benchmarks for the remainder of the autumn season.