The European Central Bank (ECB) raised its main deposit facility rate to 2.5% on September 10, 2026, as it attempts to anchor inflation expectations in an economy increasingly defined by external supply shocks. With euro area inflation currently reported at 3.3%, the central bank remains significantly above its 2% target, even as its primary tool—interest rate adjustments—faces diminishing effectiveness against non-monetary pressures.
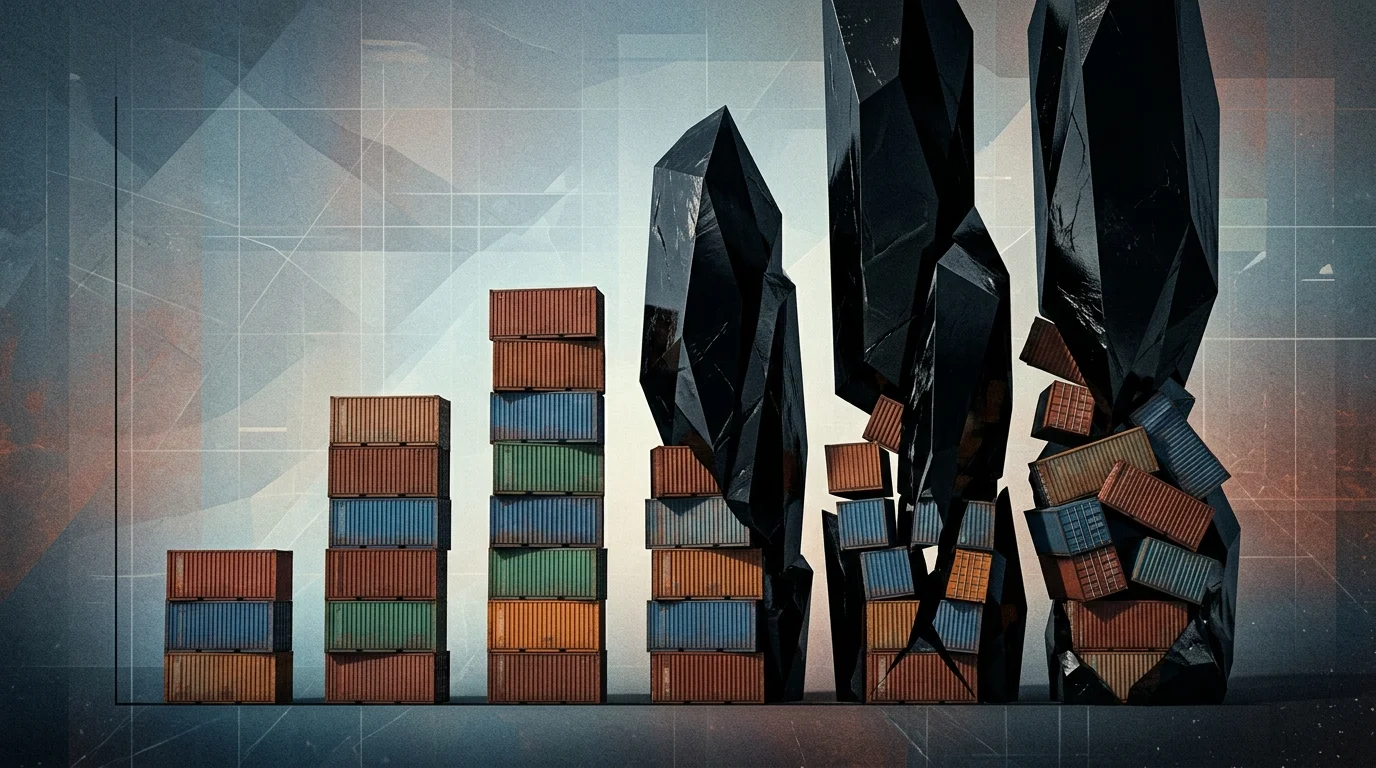
The core challenge for central banks in late 2026 is a transition from “monetary dominance” to a “resilience dependency.” Policy leaders are finding that while interest rates can dampen consumer demand, they cannot reopen shipping lanes or lower the “crack spread” in refining margins. This shift places the burden of economic stability on structural and fiscal reforms rather than central bank intervention alone.
Supply Shocks and the Limits of Interest Rates
Current inflationary pressures are largely tied to energy costs following the February 28, 2026, strikes on Tehran, which led to the closure of the Strait of Hormuz. This geopolitical disruption has kept energy prices elevated; oil prices closed at $92.60 per barrel in New York on September 28, 2026. For the ECB, these costs represent a “supply shock” that higher interest rates cannot directly mitigate.
According to ECB staff projections, headline inflation is expected to average 3.0% for the full year of 2026, eventually cooling to 2.5% in 2027. However, these forecasts rely on the assumption of a resilient economic framework that can withstand further volatility. Without such resilience, central banks are forced to choose between aggressive rate hikes that risk triggering a solvency crisis or allowing inflation to persist above target levels.
The Bank for International Settlements (BIS) has warned that the “fiscal-financial stability nexus” is tightening. High levels of public debt, combined with a surge in leveraged investment, have limited the maneuverability of monetary policy. Specifically, the BIS notes that 10% of total firm investment in 2026 is now devoted to AI-related infrastructure. While this represents a potential long-term productivity gain, the concentration of capital in this sector has created a new source of financial volatility that complicates the task of cooling the broader economy.
The Shift Toward Structural Resilience
The limitation of monetary policy is most evident in its inability to address specific industrial bottlenecks. In the energy sector, the destruction of refining capacity and shifting trade routes have made refining margins a primary driver of the consumer price index. Central banks have no mechanism to increase refining output or secure maritime corridors; these are structural issues that require preventive government action and fiscal strategy.
Analysis of the 2026 economic landscape suggests that central banks are increasingly becoming hostage to events they cannot control. While Christine Lagarde has described the euro area economy as resilient, the BIS maintains that sovereign bond markets remain fragile. This fragility suggests that any further rate hikes intended to combat supply-driven inflation could inadvertently destabilize the financial systems they are meant to protect.
In this environment, the era of the central bank “saving the day” via liquidity and rate cuts appears to be yielding to a period where economic survival depends on the underlying strength of a nation’s infrastructure and its ability to absorb external shocks. Without these structural foundations, central banks are left with a narrowing set of choices that offer no easy path to price stability.